Weekly Market Commentary
Week in Review
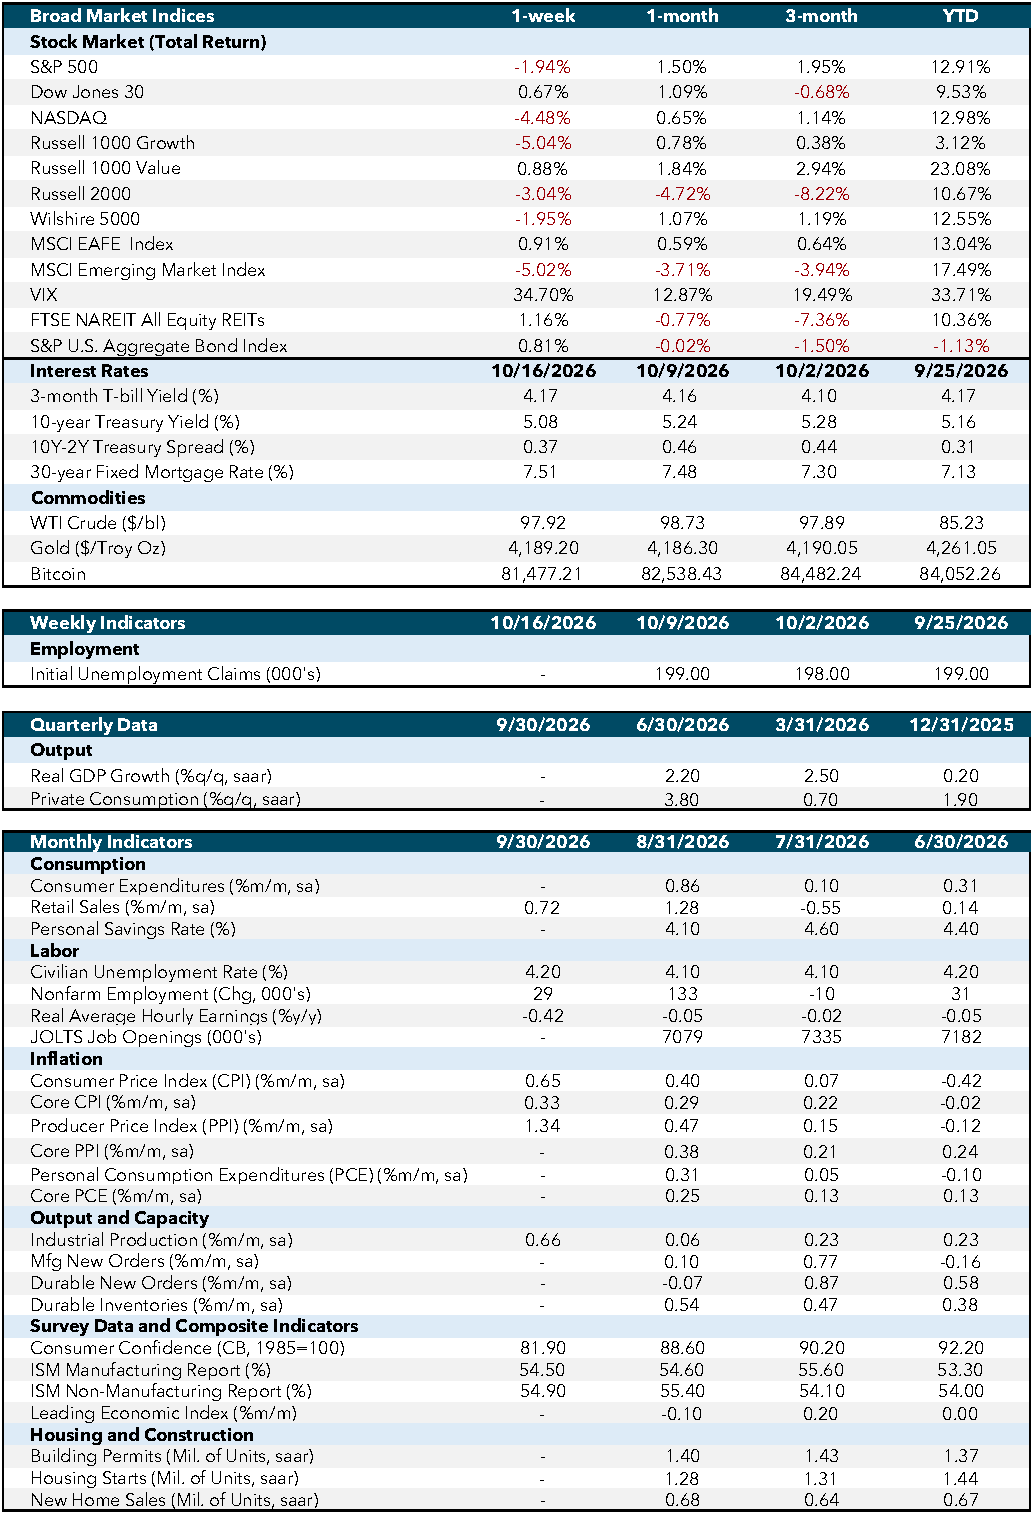
U.S. inflation accelerated in September, reflecting higher energy prices and persistent underlying price pressures. The Consumer Price Index (CPI) increased 0.6% month-over-month, bringing the annual inflation rate to 3.7%, up from 3.4% in August. Gasoline prices surged 9.1%, accounting for more than half of the monthly increase, while shelter costs rose 0.4%. Core CPI, which excludes food and energy, increased 0.3% for the month and 2.6% year-over-year. Producer inflation also came in hotter than expected, with the Producer Price Index (PPI) rising 1.3% month-over-month, significantly above the 0.6% consensus estimate and marking its largest monthly increase since March 2022. Core PPI increased 0.7%, suggesting that price pressures are extending beyond energy.
Consumer spending continued to demonstrate resilience, although underlying demand showed signs of moderation. September retail sales rose 0.8% month-over-month, exceeding expectations of 0.3%, while sales excluding autos increased 0.9%. However, higher gasoline prices contributed to the headline figures, and the retail sales control group increased just 0.1%, suggesting softer underlying consumption. Meanwhile, September existing home sales increased 1.5% to an annualized pace of 3.99 million units, despite continued affordability challenges and elevated mortgage rates. Labor market conditions remained relatively stable, with initial jobless claims totaling 199,000, broadly in line with expectations.
The Federal Reserve’s latest Beige Book, released Wednesday, indicated that economic activity expanded slightly to moderately across most districts, although consumer spending remained largely unchanged. Manufacturing activity improved in several regions, while employment growth remained modest as businesses continued to exercise caution in hiring. The report also highlighted intensifying cost pressures from energy, tariffs, and transportation, with some businesses passing higher expenses on to consumers.
Overall, the week’s economic data reinforced concerns that inflation remains elevated despite relatively stable economic activity. With headline inflation moving further above the Fed’s 2% target, policymakers face an increasingly difficult balance between containing price pressures and preserving economic growth ahead of the October 27-28 Federal Open Market Committee (FOMC) meeting.
Economic and Capital Markets Dashboard
Week Ahead
The upcoming week features a lighter economic calendar, with attention focused on housing activity, labor market conditions, and preliminary business activity indicators. September housing starts and building permits will provide an updated assessment of residential construction amid elevated mortgage rates, rising material costs, and persistent affordability constraints. Housing starts are expected to show a modest rebound following recent weakness, although continued pressure on builders and prospective buyers could limit the recovery. Additional housing indicators will help assess whether demand is stabilizing heading into the final quarter of the year.
Labor market conditions will remain in focus, with Thursday’s weekly initial jobless claims providing insight into whether employers are beginning to reduce staffing amid rising operating costs. The Conference Board’s Leading Economic Index and the Kansas City Fed Manufacturing Survey will offer further perspective on economic momentum, particularly whether manufacturing improvements are broadening across regions.
Friday’s preliminary October S&P Global manufacturing and services Purchasing Managers’ Index (PMI) readings will be among the week’s most closely watched releases. Particular attention will be paid to new orders, employment, and input prices to assess whether inflationary pressures are becoming more persistent. The University of Michigan’s final October consumer sentiment report will also provide updated readings on household confidence and inflation expectations. With Federal Reserve officials entering their blackout period ahead of the October policy meeting, these releases will be important in assessing whether inflationary pressures are moderating or warrant additional monetary tightening.
Disclosures and Definitions
Economic Indicators:
- CPI: Consumer Price Index measures the average change in prices paid by consumers for goods and services over time. Source: Bureau of Labor Statistics.
- Core CPI: Core Consumer Price Index excludes food and energy prices to provide a clearer picture of long-term inflation trends. Source: Bureau of Labor Statistics.
- PPI: Producer Price Index measures the average change in selling prices received by domestic producers for their output. Source: Bureau of Labor Statistics.
- Core PPI: Core Producer Price Index excludes food and energy prices to provide a clearer picture of long-term inflation trends. Source: Bureau of Labor Statistics.
- PCE: Personal Consumption Expenditures measure the average change in prices paid by consumers for goods and services. Source: Bureau of Economic Analysis.
- Core PCE: Core Personal Consumption Expenditures exclude food and energy prices to provide a clearer picture of long-term inflation trends. Source: Bureau of Economic Analysis.
- Industrial Production: Measures the output of the industrial sector, including manufacturing, mining, and utilities. Source: Federal Reserve.
- Mfg New Orders: Measures the value of new orders placed with manufacturers for durable and non-durable goods. Source: Census Bureau.
- Durable New Orders: Measures the value of new orders placed with manufacturers of durable goods. Source: Census Bureau.
- Durable Inventories: Measures the value of inventories held by manufacturers for durable goods. Source: Census Bureau.
- Consumer Confidence (CB, 1985=100): Measures the degree of optimism that consumers feel about the overall state of the economy and their personal financial situation. Source: Conference Board.
- ISM Manufacturing Report: Measures the economic health of the manufacturing sector based on surveys of purchasing managers. Source: Institute for Supply Management.
- ISM Non-Manufacturing Report: Measures the economic health of the non-manufacturing sector based on surveys of purchasing managers. Source: Institute for Supply Management.
- Leading Economic Index: Measures overall economic activity and predicts future economic trends. Source: Conference Board.
- Building Permits (Mil. of Units, saar): Measures the number of new residential building permits issued. Source: Census Bureau.
- Housing Starts (Mil. of Units, saar): Measures the number of new residential construction projects that have begun. Source: Census Bureau.
- New Home Sales (Mil. of Units, saar): Measures the number of newly constructed homes sold. Source: Census Bureau.
- SA: Seasonally adjusted.
- SAAR: Seasonally adjusted annual rate.
Market Indices & Indicators:
- S&P 500: A market-capitalization-weighted index of 500 leading publicly traded companies in the U.S., widely regarded as one of the best gauges of large U.S. stocks and the stock market overall.
- Dow Jones 30: Also known as the Dow Jones Industrial Average, it tracks the share price performance of 30 large, publicly traded U.S. companies, serving as a barometer of the stock market and economy.
- NASDAQ: The world's first electronic stock exchange, primarily listing technology giants and operating 29 markets globally.
- Russell 1000 Growth: Measures the performance of large-cap growth segment of the U.S. equity universe, including companies with higher price-to-book ratios and growth metrics.
- Russell 1000 Value: Measures the performance of large-cap value segment of the U.S. equity universe, including companies with lower price-to-book ratios and growth metrics.
- Russell 2000: A market index composed of 2,000 small-cap companies, widely used as a benchmark for small-cap mutual funds.
- Wilshire 5000: A market-capitalization-weighted index capturing the performance of all American stocks actively traded in the U.S., representing the broadest measure of the U.S. stock market.
- MSCI EAFE Index: An equity index capturing large and mid-cap representation across developed markets countries around the world, excluding the U.S. and Canada.
- MSCI Emerging Market Index: Captures large and mid-cap representation across emerging markets countries, covering approximately 85% of the free float-adjusted market capitalization in each country.
- VIX: The CBOE Volatility Index measures the market’s expectations for volatility over the coming 30 days, often referred to as the "fear gauge."
- FTSE NAREIT All Equity REITs: Measures the performance of all publicly traded equity real estate investment trusts (REITs) listed in the U.S., excluding mortgage REITs.
- S&P U.S. Aggregate Bond Index: Represents the performance of the U.S. investment-grade bond market, including government, corporate, mortgage-backed, and asset-backed securities.
- 3-Month T-bill Yield (%): The yield on U.S. Treasury bills with a maturity of three months, reflecting short-term interest rates.
- 10-Year Treasury Yield (%): The yield on U.S. Treasury bonds with a maturity of ten years, reflecting long-term interest rates.
- 10Y-2Y Treasury Spread (%): The difference between the yields on 10-year and 2-year U.S. Treasury bonds, often used as an indicator of economic expectations.
- WTI Crude ($/bl): The price per barrel of West Texas Intermediate crude oil, a benchmark for U.S. oil prices.
- Gold ($/Troy Oz): The price per troy ounce of gold, a standard measure for gold prices.
- Bitcoin: A decentralized digital currency without a central bank or single administrator, which can be sent from user to user on the peer-to-peer bitcoin network.
This content was developed by Cambridge and BridgePort from sources believed to be reliable. This content is provided for informational purposes only and should not be construed or acted upon as individualized investment advice. It should not be considered a recommendation or solicitation. Information is subject to change. Any forward-looking statements are based on assumptions, may not materialize, and are subject to revision without notice. The information in this material is not intended as tax or legal advice.
Investing involves risk. Depending on the different types of investments there may be varying degrees of risk. Socially responsible investing does not guarantee any amount of success. Clients and prospective clients should be prepared to bear investment loss including loss of original principal. Indices mentioned are unmanaged and cannot be invested into directly. Past performance is not a guarantee of future results.
The Dow Jones Industrial Average (DJIA) is a price-weighted index composed of 30 widely traded blue-chip U.S. common stocks. The S&P 500 is a market-cap weighted index composed of the common stocks of 500 leading companies in leading industries of the U.S. economy. The NASDAQ Composite Index is a market-value weighted index of all common stocks listed on the NASDAQ stock exchange.
Securities offered through Cambridge Investment Research, Inc., a broker-dealer, member FINRA/SIPC, and investment advisory services offered through Cambridge Investment Research Advisors, Inc., a Registered Investment Adviser. BridgePort Financial Solutions, LLC is a Registered Investment Adviser with the U.S. Securities & Exchange Commission. All three are wholly-owned subsidiaries of Cambridge Investment Group, Inc. V.CIR.1026-3881
Cambridge Investment Research, Inc.
1776 Pleasant Plain Road, Fairfield, IA 52556-8757
Business Development: 877.688.2369
Reception: 800.777.6080


