Weekly Market Commentary
Week in Review
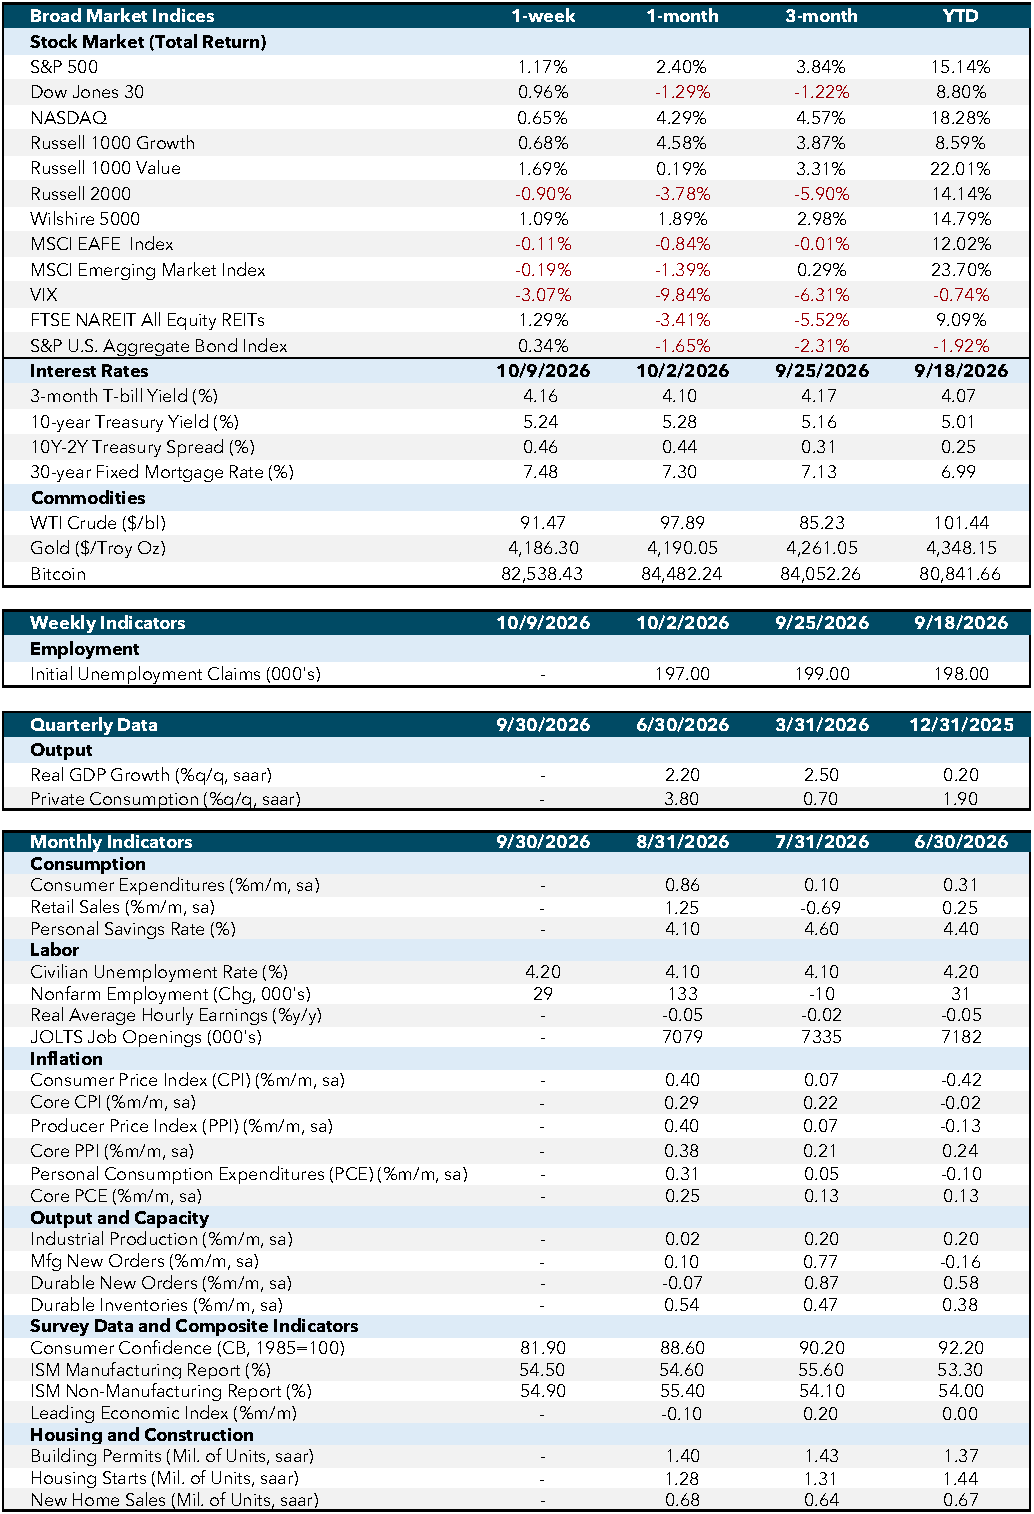
The economic data last week continued to point to a resilient U.S. economy, although the latest readings showed some moderation in service-sector activity alongside continued price pressures.
Monday’s Services Purchasing Managers’ Index (PMI) came in at 58.8 in September, slightly above both the 58.7 forecast and the prior reading. The Institute for Supply Management (ISM) Non-Manufacturing PMI was somewhat softer, declining to 54.9 from 55.4 and coming in below the 55.1 forecast. Despite the slowdown in activity, the ISM Non-Manufacturing Prices Index increased to 74.0 from 72.6, exceeding expectations of 73.3. Taken together, the data showed continued expansion across the service economy, but with price pressures remaining elevated and potentially complicating the broader inflation outlook.
Wednesday’s crude oil inventory report showed inventories declining by 3.186 million barrels, a significant contrast to expectations for a 1.9-million-barrel increase and the prior week’s 922,000-barrel build. Treasury markets were also in focus, with the 10-year note auction clearing at 5.300%, up sharply from 4.834% at the previous auction. The higher auction yield reflected a notable move upward from the prior offering and kept longer-term interest rates in focus.
Thursday’s labor-market data remained relatively steady, with initial jobless claims coming in at 197,000, below the 200,000 forecast and slightly below the prior week’s 199,000 reading. Longer-term Treasury yields were also higher at auction, with the 30-year bond clearing at 5.618%, up from 5.308% previously.
Overall, the week’s data continued to show resilience across services and the labor market, while elevated service-sector pricing and higher Treasury auction yields remained important areas to monitor as investors evaluate the direction of inflation and broader economic conditions.
Economic and Capital Markets Dashboard
Week Ahead
The week of October 12 will be highlighted by several important economic releases focused on inflation, consumer spending, labor market conditions, and housing activity. Inflation will likely remain the primary area of focus, with both Consumer Price Index (CPI) and Producer Price Index (PPI) providing investors with an updated look at whether price pressures are continuing to build heading further into the fourth quarter.
Wednesday’s CPI report is expected to show headline inflation rising 0.6% month over month and 3.6% year over year in September, up from 0.4% and 3.4% previously. Core CPI is expected to increase a more moderate 0.2%. The combination of headline and core inflation should help investors assess whether price pressures are becoming more widespread or remain concentrated in more volatile categories. Thursday’s PPI report will provide an additional look at inflationary pressures at the producer level.
Attention will also turn toward the health of the consumer and broader economy. Thursday’s retail sales report should provide insight into whether consumer spending remains resilient, while initial jobless claims will offer another timely measure of labor market conditions. The Philadelphia Fed Manufacturing Index will provide an update on manufacturing activity, while Tuesday’s existing home sales report should help investors gauge the strength of housing demand.
Crude oil inventory data will provide another look at energy market conditions, while Fed Governor Warsh is scheduled to speak Thursday. Investors will likely monitor the remarks for additional perspective on monetary policy and the economic outlook. Overall, the week should provide a broader read on whether economic conditions remain resilient while inflation continues to influence the outlook for interest rates.
Disclosures and Definitions
Economic Indicators:
- CPI: Consumer Price Index measures the average change in prices paid by consumers for goods and services over time. Source: Bureau of Labor Statistics.
- Core CPI: Core Consumer Price Index excludes food and energy prices to provide a clearer picture of long-term inflation trends. Source: Bureau of Labor Statistics.
- PPI: Producer Price Index measures the average change in selling prices received by domestic producers for their output. Source: Bureau of Labor Statistics.
- Core PPI: Core Producer Price Index excludes food and energy prices to provide a clearer picture of long-term inflation trends. Source: Bureau of Labor Statistics.
- PCE: Personal Consumption Expenditures measure the average change in prices paid by consumers for goods and services. Source: Bureau of Economic Analysis.
- Core PCE: Core Personal Consumption Expenditures exclude food and energy prices to provide a clearer picture of long-term inflation trends. Source: Bureau of Economic Analysis.
- Industrial Production: Measures the output of the industrial sector, including manufacturing, mining, and utilities. Source: Federal Reserve.
- Mfg New Orders: Measures the value of new orders placed with manufacturers for durable and non-durable goods. Source: Census Bureau.
- Durable New Orders: Measures the value of new orders placed with manufacturers of durable goods. Source: Census Bureau.
- Durable Inventories: Measures the value of inventories held by manufacturers for durable goods. Source: Census Bureau.
- Consumer Confidence (CB, 1985=100): Measures the degree of optimism that consumers feel about the overall state of the economy and their personal financial situation. Source: Conference Board.
- ISM Manufacturing Report: Measures the economic health of the manufacturing sector based on surveys of purchasing managers. Source: Institute for Supply Management.
- ISM Non-Manufacturing Report: Measures the economic health of the non-manufacturing sector based on surveys of purchasing managers. Source: Institute for Supply Management.
- Leading Economic Index: Measures overall economic activity and predicts future economic trends. Source: Conference Board.
- Building Permits (Mil. of Units, saar): Measures the number of new residential building permits issued. Source: Census Bureau.
- Housing Starts (Mil. of Units, saar): Measures the number of new residential construction projects that have begun. Source: Census Bureau.
- New Home Sales (Mil. of Units, saar): Measures the number of newly constructed homes sold. Source: Census Bureau.
- SA: Seasonally adjusted.
- SAAR: Seasonally adjusted annual rate.
Market Indices & Indicators:
- S&P 500: A market-capitalization-weighted index of 500 leading publicly traded companies in the U.S., widely regarded as one of the best gauges of large U.S. stocks and the stock market overall.
- Dow Jones 30: Also known as the Dow Jones Industrial Average, it tracks the share price performance of 30 large, publicly traded U.S. companies, serving as a barometer of the stock market and economy.
- NASDAQ: The world's first electronic stock exchange, primarily listing technology giants and operating 29 markets globally.
- Russell 1000 Growth: Measures the performance of large-cap growth segment of the U.S. equity universe, including companies with higher price-to-book ratios and growth metrics.
- Russell 1000 Value: Measures the performance of large-cap value segment of the U.S. equity universe, including companies with lower price-to-book ratios and growth metrics.
- Russell 2000: A market index composed of 2,000 small-cap companies, widely used as a benchmark for small-cap mutual funds.
- Wilshire 5000: A market-capitalization-weighted index capturing the performance of all American stocks actively traded in the U.S., representing the broadest measure of the U.S. stock market.
- MSCI EAFE Index: An equity index capturing large and mid-cap representation across developed markets countries around the world, excluding the U.S. and Canada.
- MSCI Emerging Market Index: Captures large and mid-cap representation across emerging markets countries, covering approximately 85% of the free float-adjusted market capitalization in each country.
- VIX: The CBOE Volatility Index measures the market’s expectations for volatility over the coming 30 days, often referred to as the "fear gauge."
- FTSE NAREIT All Equity REITs: Measures the performance of all publicly traded equity real estate investment trusts (REITs) listed in the U.S., excluding mortgage REITs.
- S&P U.S. Aggregate Bond Index: Represents the performance of the U.S. investment-grade bond market, including government, corporate, mortgage-backed, and asset-backed securities.
- 3-Month T-bill Yield (%): The yield on U.S. Treasury bills with a maturity of three months, reflecting short-term interest rates.
- 10-Year Treasury Yield (%): The yield on U.S. Treasury bonds with a maturity of ten years, reflecting long-term interest rates.
- 10Y-2Y Treasury Spread (%): The difference between the yields on 10-year and 2-year U.S. Treasury bonds, often used as an indicator of economic expectations.
- WTI Crude ($/bl): The price per barrel of West Texas Intermediate crude oil, a benchmark for U.S. oil prices.
- Gold ($/Troy Oz): The price per troy ounce of gold, a standard measure for gold prices.
- Bitcoin: A decentralized digital currency without a central bank or single administrator, which can be sent from user to user on the peer-to-peer bitcoin network.
This content was developed by Cambridge and BridgePort from sources believed to be reliable. This content is provided for informational purposes only and should not be construed or acted upon as individualized investment advice. It should not be considered a recommendation or solicitation. Information is subject to change. Any forward-looking statements are based on assumptions, may not materialize, and are subject to revision without notice. The information in this material is not intended as tax or legal advice.
Investing involves risk. Depending on the different types of investments there may be varying degrees of risk. Socially responsible investing does not guarantee any amount of success. Clients and prospective clients should be prepared to bear investment loss including loss of original principal. Indices mentioned are unmanaged and cannot be invested into directly. Past performance is not a guarantee of future results.
The Dow Jones Industrial Average (DJIA) is a price-weighted index composed of 30 widely traded blue-chip U.S. common stocks. The S&P 500 is a market-cap weighted index composed of the common stocks of 500 leading companies in leading industries of the U.S. economy. The NASDAQ Composite Index is a market-value weighted index of all common stocks listed on the NASDAQ stock exchange.
Securities offered through Cambridge Investment Research, Inc., a broker-dealer, member FINRA/SIPC, and investment advisory services offered through Cambridge Investment Research Advisors, Inc., a Registered Investment Adviser. BridgePort Financial Solutions, LLC is a Registered Investment Adviser with the U.S. Securities & Exchange Commission. All three are wholly-owned subsidiaries of Cambridge Investment Group, Inc. V.CIR.1026-3801
Cambridge Investment Research, Inc.
1776 Pleasant Plain Road, Fairfield, IA 52556-8757
Business Development: 877.688.2369
Reception: 800.777.6080


