Weekly Market Commentary
The Week in Review
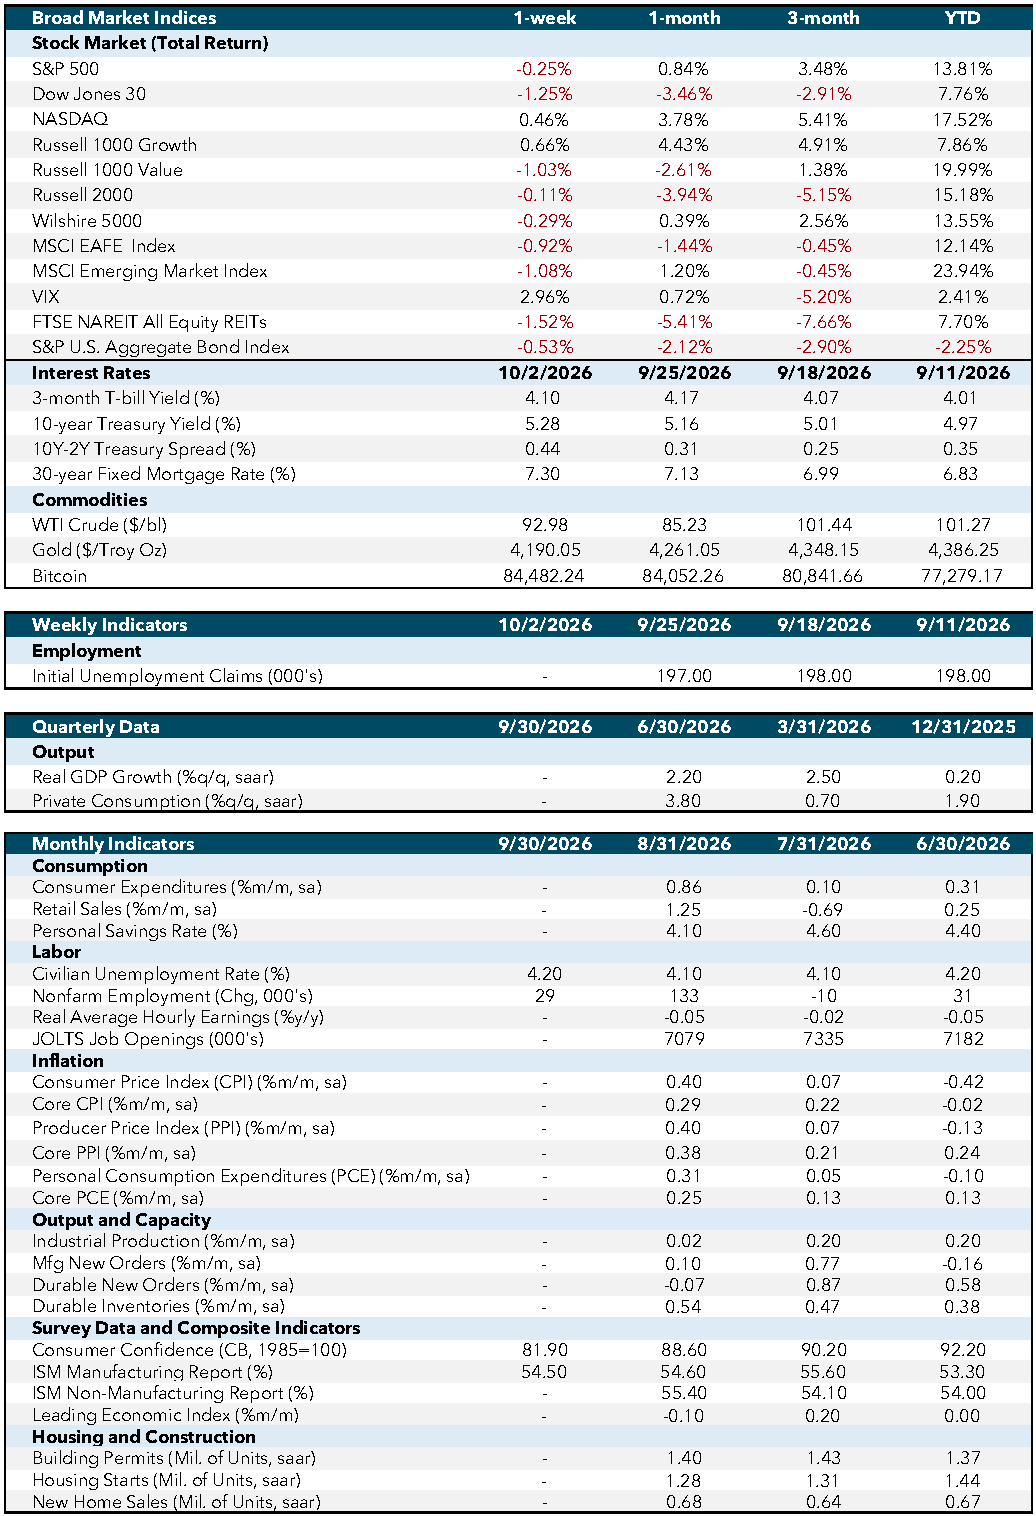
Inflation came in below expectations and Q2 U.S. gross domestic product (GDP) growth exceeded forecasts, while labor data pointed to slower hiring. Together, the releases showed continued economic expansion alongside moderating labor demand and inflation above the Federal Reserve’s target.
Inflation: Softer Than Expected but Still Above Target
Personal consumption expenditures (PCE) data, the Federal Reserve’s preferred inflation gauge, came in softer than expected for August. Headline PCE rose 0.3% month over month versus an expected 0.4%, and 3.4% year over year versus an expected 3.7%. Core PCE, which excludes more volatile food and energy costs, increased 0.2% month over month versus an expected 0.3%, and 3.0% year over year versus an expected 3.3%. The data reflect price increases in other nondurable goods, gas and energy goods, and food services, which were the largest increases. The updated figures reflect the Bureau of Economic Analysis’ revisions to how it calculates the index, including changes to price measurements for legal services, software, and portfolio management.
Despite the softer readings, the figures continue to show that inflation remains above the Fed’s 2% target. The Fed raised rates by 0.25 percentage points in September to a range of 3.75%-4.00%, with markets predicting a 78% chance that the Fed remains on hold at the next October meeting.
Economic Activity: Growth and Manufacturing Remain Firm
Second-quarter real GDP grew at a 2.2% annualized rate versus an expected 1.5%, supported by consumer spending, business investment, and exports, while higher imports were a headwind. Separately, the Institute for Supply Management® (ISM) Manufacturing Purchasing Managers’ Index® (PMI) eased to 54.5 versus an expected 54.8, but remained above the expansion threshold of 50. New orders, production, employment, and supplier deliveries remained in expansion territory, while the prices component jumped as a result of tightening supply amid respondents’ concerns of higher costs due to tariffs and the war in Iran.
Labor Market: Hiring Slows as Layoffs Remain Limited
September non-farm payrolls surprised sharply to the downside with 29,000 jobs added versus an expected 89,000, down from 133,000 in August. Unemployment edged up to 4.2% versus an expected 4.1%. Job Openings and Labor Turnover Survey (JOLTS) openings declined to 7.079 million from 7.335 million and were below the 7.230 million estimate. Initial jobless claims were 197,000 versus an expected 201,000, and continuing claims were down to 1.701 million versus an expected 1.730 million. The figures point to slower hiring while layoffs remained contained, consistent with a “low hire, low fire” environment.
Economic and Capital Markets Dashboard
The Week Ahead
The coming week will provide updates on service-sector activity and the Federal Reserve’s policy discussions.
Services Activity: Monitoring the Pass-Through of Higher Prices
Markets will look to the ISM Services PMI for evidence that service-sector activity remains in expansion. The report will provide additional context on how higher prices are feeding into the service sector.
Federal Reserve: Assessing the Path for Further Rate Hikes
The Federal Open Market Committee (FOMC) minutes will provide details on how policymakers assessed inflation, employment, and the potential path of rate hikes through year-end. Markets will focus on commentary about further rate hikes as recent cooler inflation and employment data shape expectations.
Disclosures and Definitions
Economic Indicators:
- CPI: Consumer Price Index measures the average change in prices paid by consumers for goods and services over time. Source: Bureau of Labor Statistics.
- Core CPI: Core Consumer Price Index excludes food and energy prices to provide a clearer picture of long-term inflation trends. Source: Bureau of Labor Statistics.
- PPI: Producer Price Index measures the average change in selling prices received by domestic producers for their output. Source: Bureau of Labor Statistics.
- Core PPI: Core Producer Price Index excludes food and energy prices to provide a clearer picture of long-term inflation trends. Source: Bureau of Labor Statistics.
- PCE: Personal Consumption Expenditures measure the average change in prices paid by consumers for goods and services. Source: Bureau of Economic Analysis.
- Core PCE: Core Personal Consumption Expenditures exclude food and energy prices to provide a clearer picture of long-term inflation trends. Source: Bureau of Economic Analysis.
- Industrial Production: Measures the output of the industrial sector, including manufacturing, mining, and utilities. Source: Federal Reserve.
- Mfg New Orders: Measures the value of new orders placed with manufacturers for durable and non-durable goods. Source: Census Bureau.
- Durable New Orders: Measures the value of new orders placed with manufacturers of durable goods. Source: Census Bureau.
- Durable Inventories: Measures the value of inventories held by manufacturers for durable goods. Source: Census Bureau.
- Consumer Confidence (CB, 1985=100): Measures the degree of optimism that consumers feel about the overall state of the economy and their personal financial situation. Source: Conference Board.
- ISM Manufacturing Report: Measures the economic health of the manufacturing sector based on surveys of purchasing managers. Source: Institute for Supply Management.
- ISM Non-Manufacturing Report: Measures the economic health of the non-manufacturing sector based on surveys of purchasing managers. Source: Institute for Supply Management.
- Leading Economic Index: Measures overall economic activity and predicts future economic trends. Source: Conference Board.
- Building Permits (Mil. of Units, saar): Measures the number of new residential building permits issued. Source: Census Bureau.
- Housing Starts (Mil. of Units, saar): Measures the number of new residential construction projects that have begun. Source: Census Bureau.
- New Home Sales (Mil. of Units, saar): Measures the number of newly constructed homes sold. Source: Census Bureau.
- SA: Seasonally adjusted.
- SAAR: Seasonally adjusted annual rate.
Market Indices & Indicators:
- S&P 500: A market-capitalization-weighted index of 500 leading publicly traded companies in the U.S., widely regarded as one of the best gauges of large U.S. stocks and the stock market overall.
- Dow Jones 30: Also known as the Dow Jones Industrial Average, it tracks the share price performance of 30 large, publicly traded U.S. companies, serving as a barometer of the stock market and economy.
- NASDAQ: The world's first electronic stock exchange, primarily listing technology giants and operating 29 markets globally.
- Russell 1000 Growth: Measures the performance of large-cap growth segment of the U.S. equity universe, including companies with higher price-to-book ratios and growth metrics.
- Russell 1000 Value: Measures the performance of large-cap value segment of the U.S. equity universe, including companies with lower price-to-book ratios and growth metrics.
- Russell 2000: A market index composed of 2,000 small-cap companies, widely used as a benchmark for small-cap mutual funds.
- Wilshire 5000: A market-capitalization-weighted index capturing the performance of all American stocks actively traded in the U.S., representing the broadest measure of the U.S. stock market.
- MSCI EAFE Index: An equity index capturing large and mid-cap representation across developed markets countries around the world, excluding the U.S. and Canada.
- MSCI Emerging Market Index: Captures large and mid-cap representation across emerging markets countries, covering approximately 85% of the free float-adjusted market capitalization in each country.
- VIX: The CBOE Volatility Index measures the market’s expectations for volatility over the coming 30 days, often referred to as the "fear gauge."
- FTSE NAREIT All Equity REITs: Measures the performance of all publicly traded equity real estate investment trusts (REITs) listed in the U.S., excluding mortgage REITs.
- S&P U.S. Aggregate Bond Index: Represents the performance of the U.S. investment-grade bond market, including government, corporate, mortgage-backed, and asset-backed securities.
- 3-Month T-bill Yield (%): The yield on U.S. Treasury bills with a maturity of three months, reflecting short-term interest rates.
- 10-Year Treasury Yield (%): The yield on U.S. Treasury bonds with a maturity of ten years, reflecting long-term interest rates.
- 10Y-2Y Treasury Spread (%): The difference between the yields on 10-year and 2-year U.S. Treasury bonds, often used as an indicator of economic expectations.
- WTI Crude ($/bl): The price per barrel of West Texas Intermediate crude oil, a benchmark for U.S. oil prices.
- Gold ($/Troy Oz): The price per troy ounce of gold, a standard measure for gold prices.
- Bitcoin: A decentralized digital currency without a central bank or single administrator, which can be sent from user to user on the peer-to-peer bitcoin network.
This content was developed by Cambridge and BridgePort from sources believed to be reliable. This content is provided for informational purposes only and should not be construed or acted upon as individualized investment advice. It should not be considered a recommendation or solicitation. Information is subject to change. Any forward-looking statements are based on assumptions, may not materialize, and are subject to revision without notice. The information in this material is not intended as tax or legal advice.
Investing involves risk. Depending on the different types of investments there may be varying degrees of risk. Socially responsible investing does not guarantee any amount of success. Clients and prospective clients should be prepared to bear investment loss including loss of original principal. Indices mentioned are unmanaged and cannot be invested into directly. Past performance is not a guarantee of future results.
The Dow Jones Industrial Average (DJIA) is a price-weighted index composed of 30 widely traded blue-chip U.S. common stocks. The S&P 500 is a market-cap weighted index composed of the common stocks of 500 leading companies in leading industries of the U.S. economy. The NASDAQ Composite Index is a market-value weighted index of all common stocks listed on the NASDAQ stock exchange.
Securities offered through Cambridge Investment Research, Inc., a broker-dealer, member FINRA/SIPC, and investment advisory services offered through Cambridge Investment Research Advisors, Inc., a Registered Investment Adviser. BridgePort Financial Solutions, LLC is a Registered Investment Adviser with the U.S. Securities & Exchange Commission. All three are wholly-owned subsidiaries of Cambridge Investment Group, Inc. V.CIR.1026-3697
Cambridge Investment Research, Inc.
1776 Pleasant Plain Road, Fairfield, IA 52556-8757
Business Development: 877.688.2369
Reception: 800.777.6080


